Spray Foam Removal: Why Waiting Until After March 2027 Could Cost You More

Important changes to VAT relief are approaching.
Important changes to VAT relief are approaching. If you need spray foam removed from your property, now could be the time to act before the current arrangements change.

At the Spray Foam Advice Centre, we are encouraging homeowners who already know their spray foam insulation needs to be removed to consider making arrangements sooner rather than later.

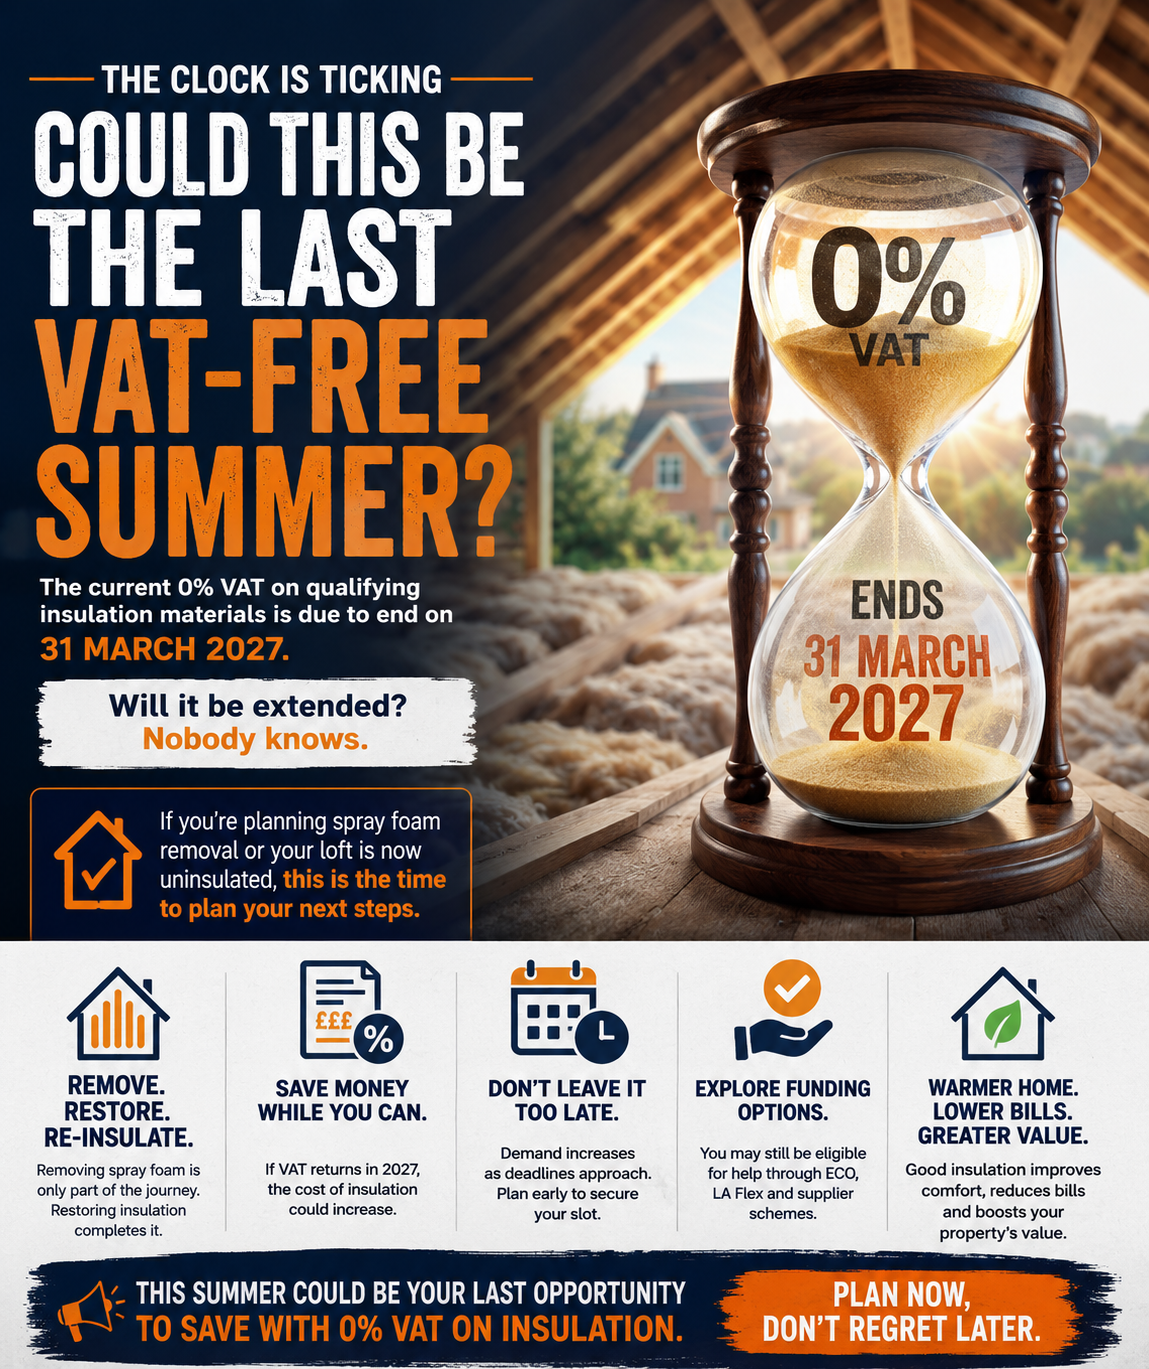
With the current temporary VAT relief on qualifying energy-saving installations scheduled to end on 31 March 2027, and significant changes already taking place across government insulation support schemes, we believe homeowners should be thinking carefully about the potential cost of delaying necessary work.

Our advice is not to panic or rush into removal, but to understand your options now, while there is still time to plan.

March 2027: An Important Deadline for Homeowners

Under the current Government arrangements, temporary VAT relief on qualifying energy-saving material installations is due to end on 31 March 2027.

Unless the Government announces an extension or further changes, VAT will apply under the arrangements in force after that date.

Importantly, the existing relief does not automatically cover standalone spray foam removal, which may already be subject to VAT.

Nevertheless, for homeowners considering removal followed by replacement insulation, the approaching deadline is something we believe should not be ignored.

Our concern is simple: waiting until 2027 could mean facing different costs for work that needs to be carried out anyway.

Government Insulation Support Is Changing

We have already seen significant changes to government-backed insulation programmes, including the closure of the Great British Insulation Scheme.

Although other energy-efficiency support remains available, the future of individual schemes and their eligibility requirements is not always clear to homeowners.

At the Spray Foam Advice Centre, we believe these developments make it sensible to review your circumstances now rather than assuming that today's arrangements will remain available indefinitely.

If Your Spray Foam Needs Removing, Why Wait?

Many homeowners contact us after experiencing problems with mortgage applications, property sales or concerns about the suitability of spray foam installed in their roofs.

Some have been considering removal for months, while others have delayed because of uncertainty about the cost or the process involved.

If you have already established that removal is necessary, our advice is to start making arrangements now.

Waiting may expose you to changes in taxation, contractor pricing and availability.

We cannot predict future prices, but we can encourage homeowners to make informed decisions before potential changes take effect.

Before You Remove Your Spray Foam, Speak to Us

There is another important consideration that homeowners should understand.

You may have options available to seek recovery of the money you originally paid for your spray foam installation, together with the costs associated with having it removed.

The Spray Foam Advice Centre has assisted homeowners who have subsequently recovered these costs after following the appropriate process for their circumstances.

Every case is different, and financial recovery cannot be guaranteed.

However, the steps taken before removal can be extremely important.

That is why we recommend speaking to our team before instructing a removal contractor.

Your Spray Foam Must Still Be Installed

Our particular pre-removal advice and cost-recovery assistance is intended for homeowners who still have spray foam installed in their property.

If your foam has already been removed, unfortunately we cannot assist through this specific service.

Once the foam has been removed, potentially important evidence relating to the original installation may no longer be available.

Don't remove it first and ask questions afterwards. Get advice before taking action.

Our Advice for Homeowners Approaching 2027

We believe the coming months provide an opportunity for homeowners to review their situation, understand their options and make arrangements where removal is necessary.

With the current VAT relief period approaching its scheduled end and government insulation programmes undergoing changes, there are good reasons not to delay unnecessarily.

That does not mean every property with spray foam requires removal.

But if your property has already been affected by mortgage restrictions, difficulties selling or concerns about the installation, now is a sensible time to seek professional guidance.

Don't Wait Until the Rules Change — Find Out Where You Stand Today

If you still have spray foam insulation installed and are considering removal, contact the Spray Foam Advice Centre before committing to any work.

Our team can help you understand the removal process and discuss potential options for recovering costs associated with the original installation and its removal.

Complete our online enquiry form today and allow one of our advisers to contact you.

You have already paid to have your spray foam installed. Before paying to have it removed, find out what options may be available to you.

Spray Foam Advice Centre — Independent advice for UK homeowners.

www.sfacuk.org

Contact Us

Share this article

By Adam Gough • October 16, 2026
Don't Wait Until You Make a Claim to Find Out You're Not Covered.
September 17, 2026
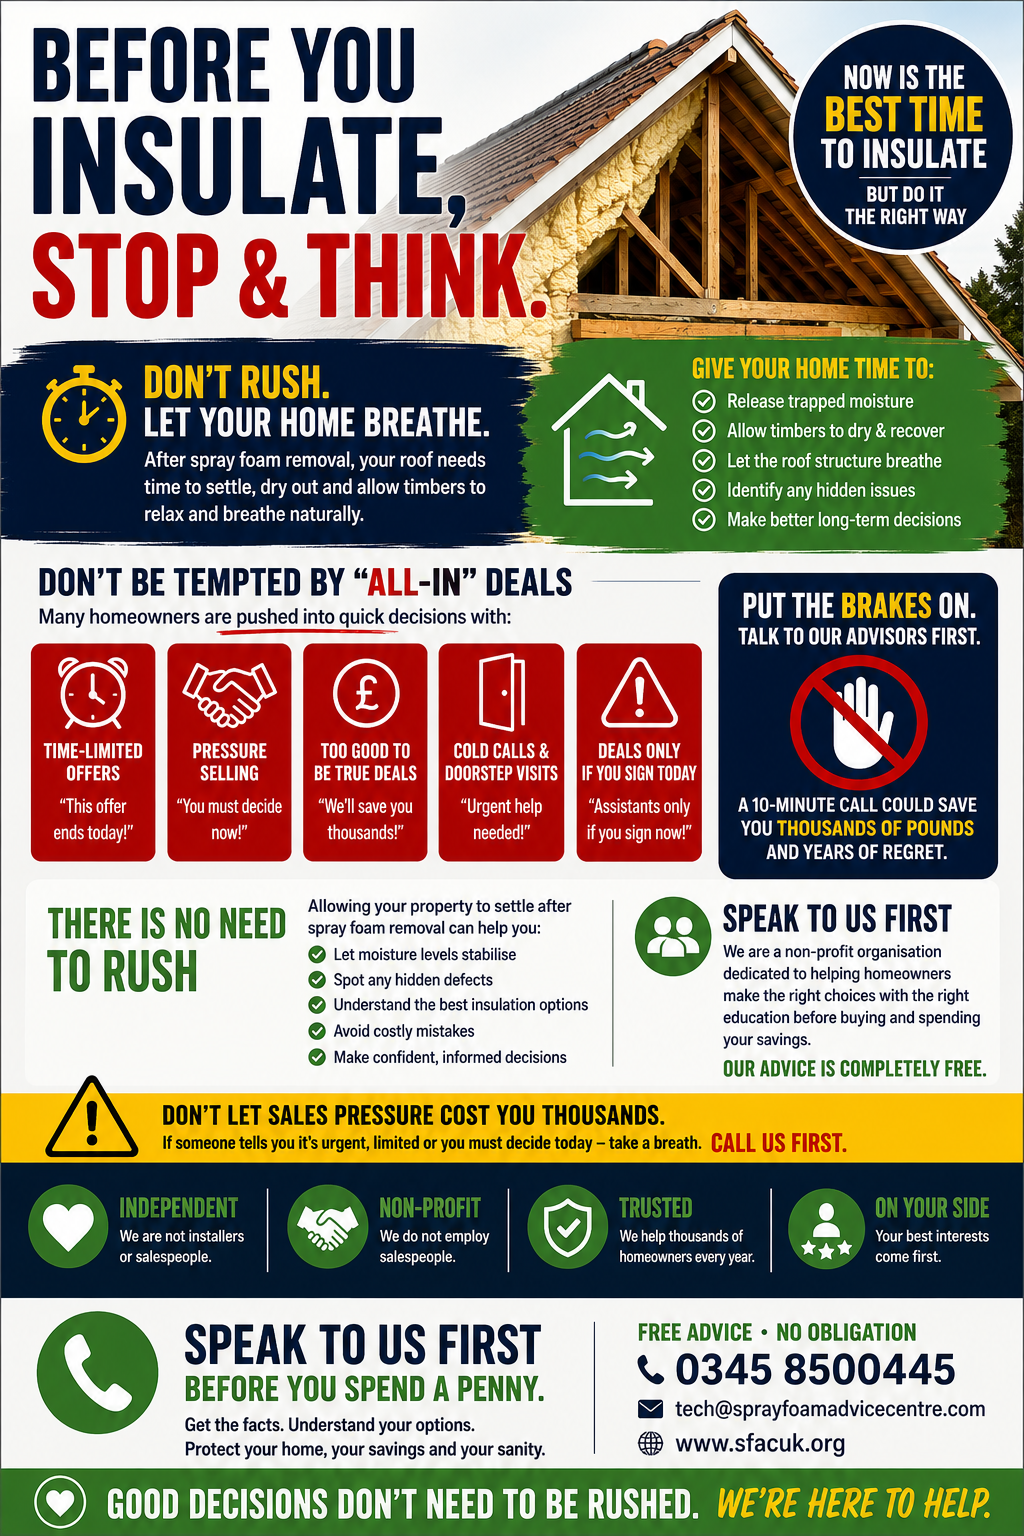
Before you spend thousands having your spray foam removed, speak to the Spray Foam Advice Centre
August 28, 2026
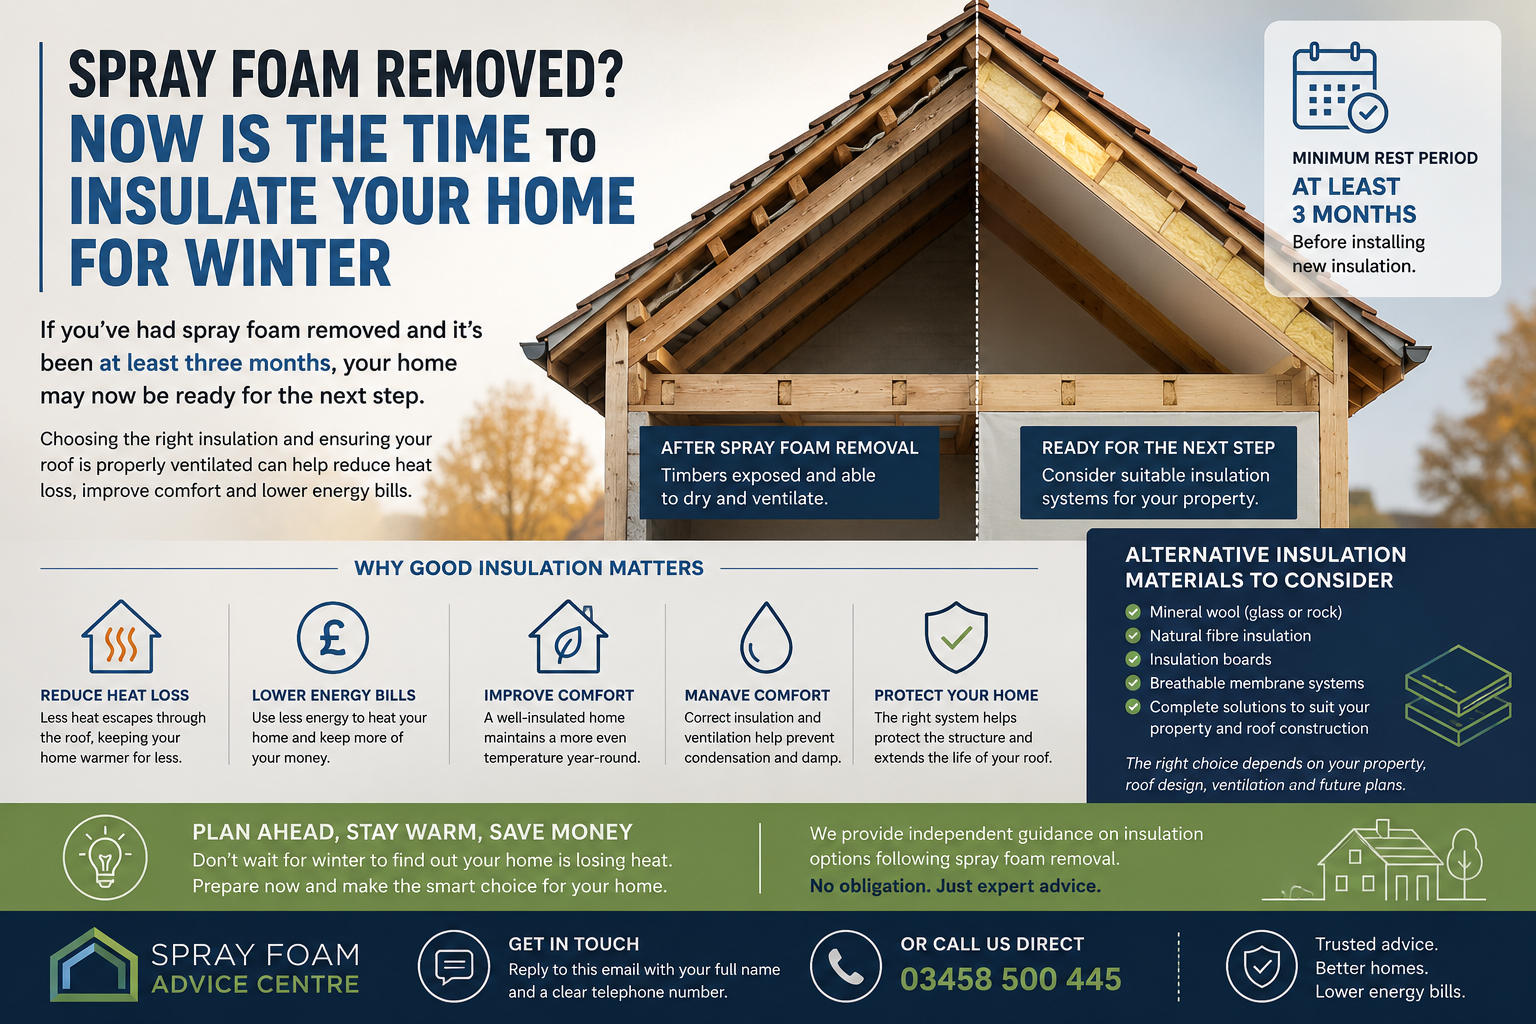
Removing Spray Foam Doesn't Remove the Need for Insulation
July 28, 2026
The Spray Foam Advice Centre's New Post-Removal Support Programme
July 28, 2026
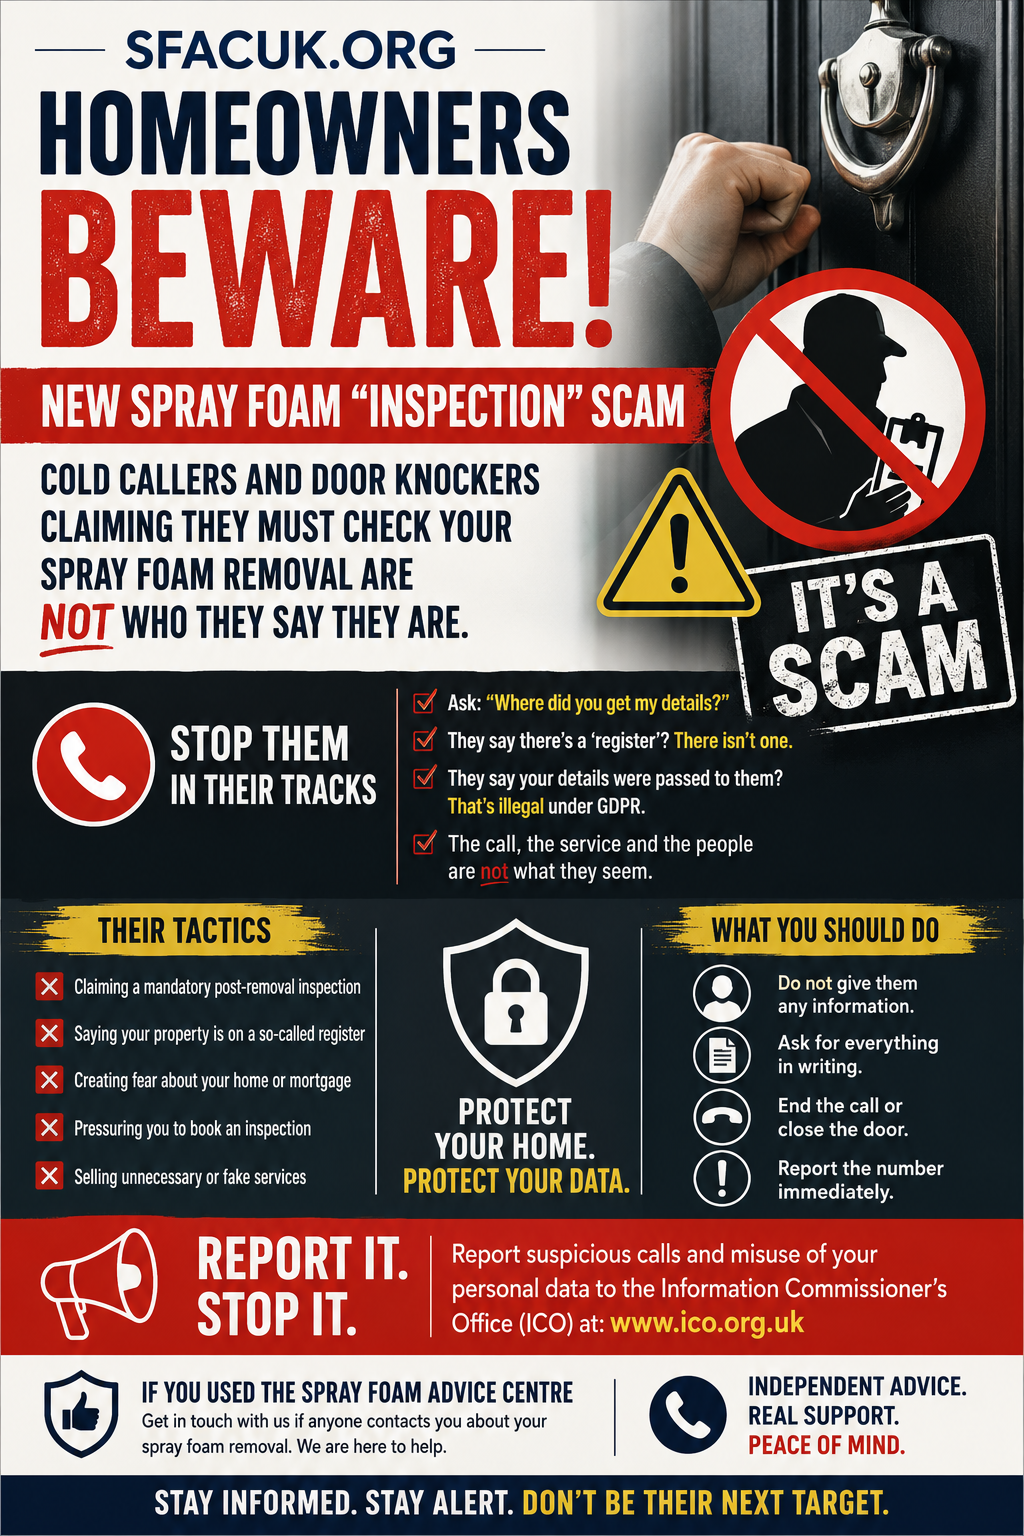
Cold Callers Are Back — This Time They're Claiming Your Spray Foam Removal Needs "Checking"
July 16, 2026
For UK homeowners, this could be one of those moments.
June 30, 2026
The Biggest Mistake Homeowners Are Making After Spray Foam Removal
June 4, 2026
Summer is by far the best season to remove spray foam insulation.
May 19, 2026
As the spray foam insulation crisis continues to affect homeowners across the UK, many people are only now discovering that they may have important legal protection under Section 75 of the Consumer Credit Act 1974. For some homeowners, this protection could prove financially life-changing. Why? Because if even part of the original spray foam installation was paid for using a credit card, homeowners may have the right to pursue claims not only for the installation itself — but potentially for associated losses, including costly removal work. At a time when many families are facing failed mortgage applications, equity release refusals, and expensive remediation bills, understanding Section 75 has become critically important. What Is Section 75? Section 75 of the Consumer Credit Act is a UK consumer protection law that makes credit card providers jointly liable for breaches of contract or misrepresentation by a retailer or service provider. In simple terms: If a company sold a product or service under misleading circumstances, and part of the payment was made using a credit card, the credit card company can also be held responsible. This protection applies even if: The company has ceased trading The installer refuses to help The warranty is worthless The homeowner only paid a deposit on the credit card Many consumers wrongly believe the entire balance must have been paid by credit card. That is not true. In many cases, paying just the initial deposit or first payment via credit card may be enough to trigger Section 75 protection. Why This Matters for Spray Foam Insulation Thousands of homeowners claim they were sold spray foam insulation without proper warnings about: Mortgage restrictions Lending refusals Future saleability concerns Ventilation risks Timber inspection limitations Potential removal costs Many homeowners state they were assured: “Mortgage lenders have no issue.” “The product is fully approved everywhere.” “It adds value to your home.” “It is completely safe for future buyers.” Years later, some are discovering: Their property is down-valued Equity release applications are declined Buyers cannot obtain mortgages Surveyors are flagging the roof structure Removal costs can exceed tens of thousands of pounds This is where Section 75 may become highly significant. Removal Costs May Also Form Part of a Claim One of the most important points homeowners should understand is this: Potential claims may not be limited solely to the original installation cost. If the product was misrepresented or sold without proper disclosure of foreseeable consequences, consequential losses may also be considered. This can include: Spray foam removal costs Roof timber inspection costs Surveyor reports Associated remedial works Financial losses linked to failed transactions Every claim is fact-specific, and outcomes vary, but legal and financial experts increasingly recognise that removal costs may form a substantial part of consumer claims where remediation becomes necessary to restore mortgageability. For homeowners now facing enormous removal bills simply to sell or refinance their homes, this aspect of Section 75 could be critical. The Key Requirement Many People Do Not Realise To qualify for Section 75 protection, one of the most important conditions is that at least part of the transaction must have been made directly using qualifying credit. In many spray foam cases, homeowners paid: The initial deposit by credit card Follow-up balances via bank transfer Finance agreements Debit cards Or cash The crucial point is this: If the first payment or deposit was made on a qualifying credit card, protection may still apply for the full contract value — not merely the deposit amount. This is one of the most misunderstood areas of consumer law. Homeowners Should Gather Evidence Immediately If you believe your property may be affected, it is important to begin collecting documentation as early as possible. Useful evidence may include: Original invoices Credit card statements Finance agreements Installation contracts Sales brochures Emails and WhatsApp messages Mortgage refusal letters Surveyor reports Removal quotations Guarantees and warranties Advertising claims made at the time of sale The stronger the documentary trail, the stronger the potential claim position may become. Time Is Important Many homeowners delay taking action because they assume: “Nothing can be done.” “The installer has disappeared.” “The warranty is useless.” “The problem is too old.” However, Section 75 protections can sometimes extend far beyond standard warranty periods. Each situation depends on individual facts, dates, and legal considerations, but homeowners should not automatically assume they have no options available. Awareness Could Save Homeowners Thousands For many families, spray foam insulation has become far more than an insulation issue. It has become: A lending issue A property value issue A retirement issue And in some cases, a financial survival issue Understanding Section 75 may offer an important pathway for homeowners facing unexpected financial harm linked to spray foam installations. The key message is simple: If you paid even part of the installation using a credit card, you may have more rights than you realise. Important Consumer Note This article is for general awareness only and does not constitute legal advice. Individual circumstances vary, and homeowners should seek independent legal and financial guidance regarding any potential claim. About The Spray Foam Advice Centre Spray Foam Advice Centre provides independent consumer awareness and guidance regarding spray foam insulation, mortgage concerns, remediation pathways, and homeowner support across the UK.